In Defense of the Invisible Partner: What a Good Trading Company Actually Does for Its Margin

Photo by Photo by 雙 film on Unsplash on Unsplash
No one writes songs about the trading company. In the popular imagination of global commerce, intermediaries occupy the lowest rung of respectability — somewhere between currency speculators and parking attendants. The narrative is familiar: cut out the middleman, deal direct with the factory, keep the margin for yourself.
It is a tidy story. It is also, in the experience of firms that have actually tried it, frequently wrong.
The Case Against the Middleman, Taken Seriously
Let us begin by granting the critics their strongest argument. Some intermediaries are, in fact, parasitic. They exist because they once knew a buyer or a factory, they add a percentage for access, and they contribute nothing when problems arise. In commodity categories with transparent pricing and stable quality, a pure pass-through intermediary is exactly what it appears to be: a cost with a fax machine.
The internet made this failure mode more visible and more common. When a US buyer can browse a supplier directory from a laptop in Denver, the intermediary whose only offering is a phone number adds negative value. Fair enough. But the conclusion critics draw — that intermediaries are therefore obsolete — does not follow. It merely establishes that the bar has risen.
What the Invisible Partner Actually Does
A capable trading company earns its margin in three places, none of which appear on an invoice.
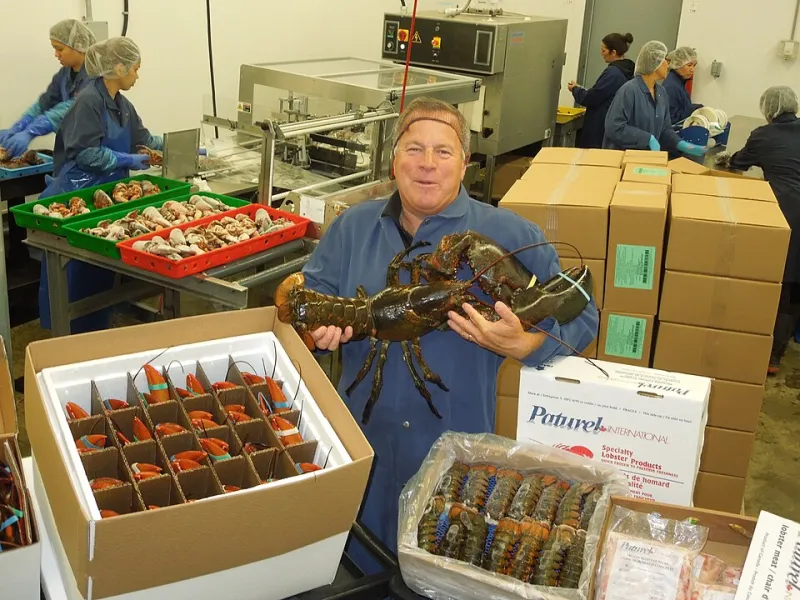
Quality control at the point of production. A US buyer dealing directly with an overseas factory typically learns about a quality failure when the container is opened. A trading firm embedded in the sourcing market learns about it while the goods are still on the line. Proximity to production — speaking the language, visiting the floor, knowing which subcontractor the factory quietly uses when orders spike — converts quality from a gamble into a managed process. The cost of preventing a defective shipment is a rounding error compared to the cost of receiving one.
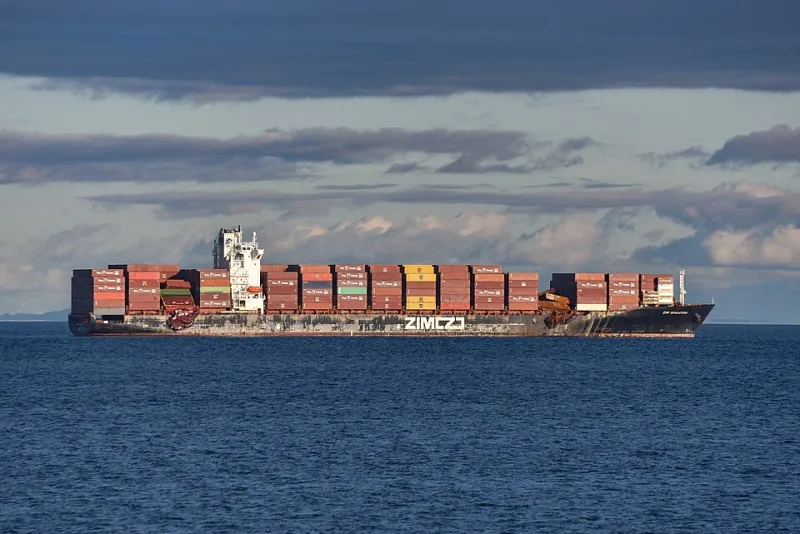
Logistics coordination across a fragmented system. Between a factory gate in Asia and a distribution center in Ohio lies a chain of handoffs: inland haulage, export clearance, ocean freight, port congestion, customs entry, drayage, final delivery. Each handoff is an opportunity for delay, demurrage, or damage. Firms that manage this chain daily have relationships with freight forwarders, knowledge of routing alternatives, and — critically — leverage when disruptions hit. The importer who ships twice a year does not have a seat at that table. The trading company does.
Market intelligence as a byproduct of volume. A trading firm moving goods across dozens of clients and suppliers sees the market's nervous system: which factories are overextended, which input costs are moving, which regions are becoming politically fragile, which "established" supplier is quietly circling the drain. This intelligence is not sold separately. It is baked into supplier selection and into the quiet warnings that arrive before problems become losses.
When the Margin Is Not Earned
The honest version of this argument requires admitting the failure conditions. A trading partner is not earning its keep when it refuses to disclose its supplier base while adding nothing beyond order placement; when it cannot produce inspection records, compliance documentation, or factory audit results on request; when its pricing is opaque by design rather than by competitive necessity; or when its involvement ends the moment the purchase order is confirmed.
Volume without accountability is not partnership. It is brokerage with better branding.
A Checklist for Evaluating the Value
Buyers weighing whether an intermediary justifies its margin should ask:
- Who performs quality inspection, and can I see the reports? Vague answers here are disqualifying.
- What happened the last time a shipment went wrong? A good partner has a story with a resolution; a bad one has a story with a shrug.
- Can the firm explain its pricing structure? Not necessarily every number — but the logic should be coherent.
- Does the firm have physical presence or audited relationships in the sourcing market? Distance correlates strongly with excuse-making.
- What does the firm know that I could not learn from a directory? If the answer is nothing, the margin is a toll.
The Verdict
The middleman is not dead, but the undifferentiated middleman is. What survives — what thrives — is the trading company that functions as an extension of the buyer's own operations: eyes on the factory floor, hands on the logistics chain, and judgment informed by market presence the buyer cannot replicate at any reasonable cost.
When an intermediary does that work, the margin is not an added expense. It is the fee for a capability the buyer would otherwise have to build. And for most American companies, building it is the far more expensive option.